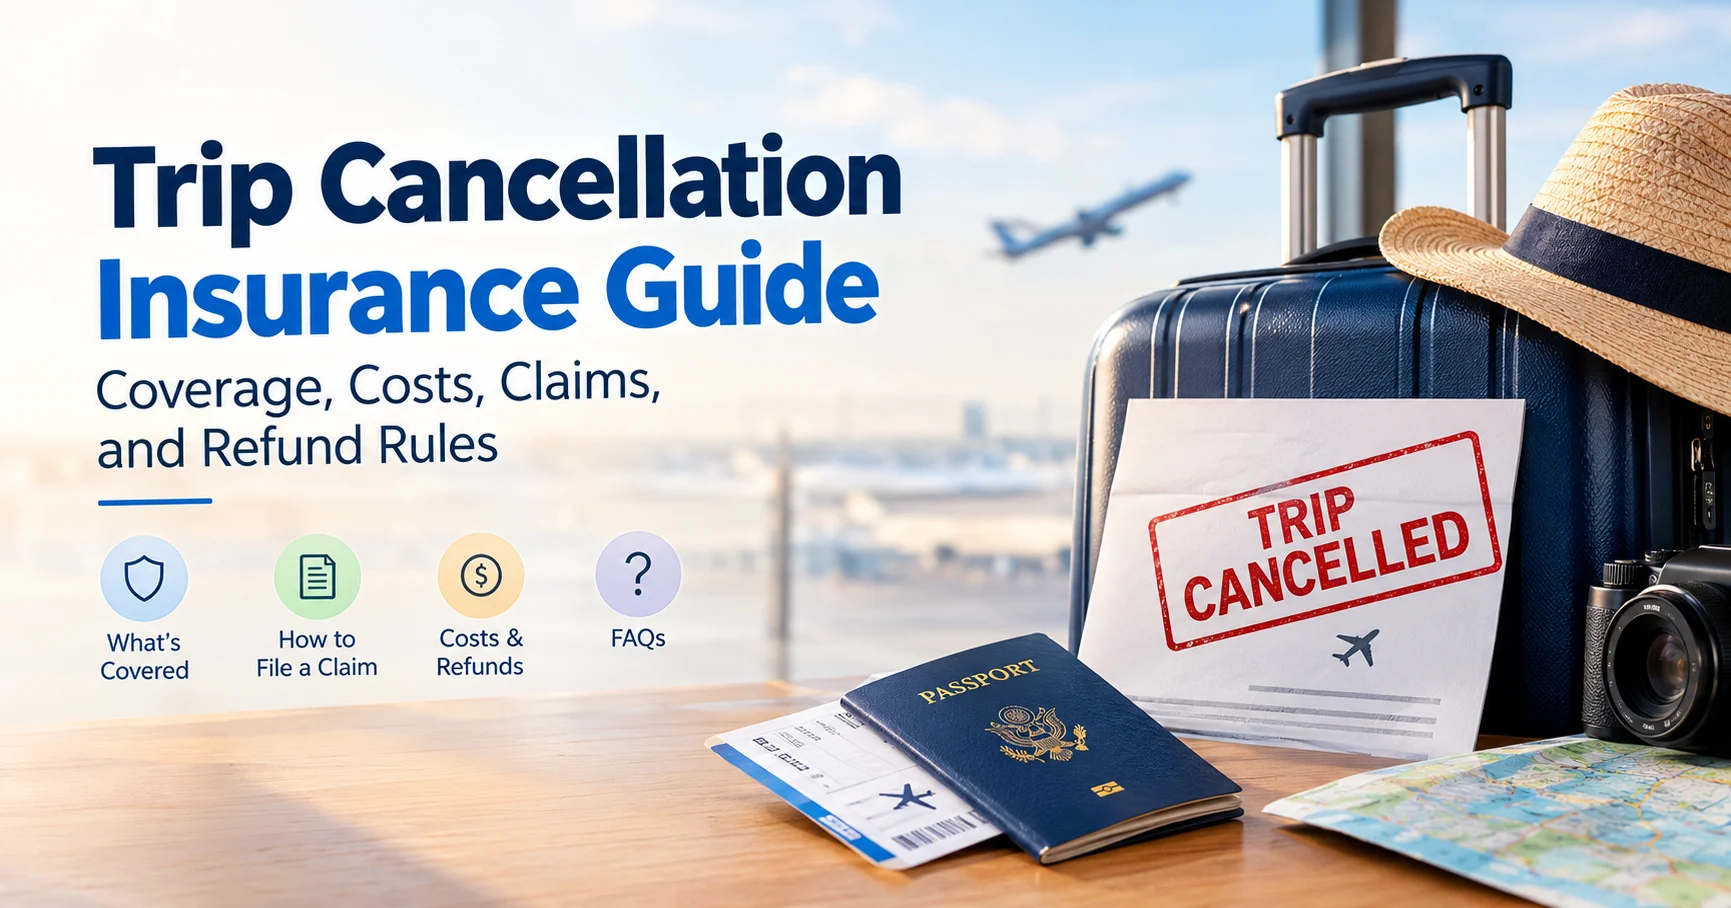
A Trip cancellation insurance guide should help you know when you can get your money back and when you may have to pay the loss yourself. A family emergency, a sudden illness, or a storm can ruin a planned trip. You may have paid for flights, hotels, tours, and cruises months in advance. Trip cancellation insurance can help recover some of these costs when the reason for cancellation meets the terms of your policy.
- What Is Trip Cancellation Insurance?
- What Does Trip Cancellation Insurance Cover?
- How to File a Claim for Trip Cancellation Insurance
- What Are the Disadvantages of Travel Insurance?
- Is Trip Cancellation Insurance Worth Buying?
- How Much Does Trip Cancellation Insurance Cost?
- Frequently Asked Questions | Trip Cancellation Insurance
What Is Trip Cancellation Insurance?
One missed trip can leave you with bills for services you never use.
Trip cancellation insurance covers certain prepaid and non-refundable travel costs if you must cancel for a reason listed in your policy. These costs may include flights, hotel stays, cruise fares, and tour bookings.
For example, you book a family holiday and pay $4,000 upfront. A few days before departure, your doctor says you cannot travel due to a serious illness. If your plan covers this event, you may claim eligible costs that the airline or hotel will not refund.
However, each policy has its own rules, limits, and exclusions. Read these terms before you buy.
What Does Trip Cancellation Insurance Cover?
The reason for cancellation matters as much as the amount you paid.
Many plans cover events such as:
- Serious illness or injury: You or a covered travel partner cannot travel due to a medical issue.
- Death in the family: A covered death may allow you to cancel.
- Severe weather: A storm or other covered event disrupts your trip.
- Home damage: Fire or another listed event makes your home unfit to live in.
- Jury duty: A court order may prevent you from leaving.
- Other listed events: Some plans cover job loss or other specific emergencies.
Check who counts as a family member under your plan. Also, check the rules for pre-existing health conditions.
How to File a Claim for Trip Cancellation Insurance
Good records can help you avoid delays and answer the insurer’s questions.
Step 1: Check your policy. Find the covered reasons for cancellation. Make sure your situation meets the rules.
Step 2: Cancel your bookings. Contact the airline, hotel, cruise line, or travel agent as soon as you can. Ask for any refund or credit you can get.
Step 3: Tell your insurer. Report the claim through its website or claims team. Follow the deadline in your policy.
Step 4: Gather your proof. Keep booking receipts, payment records, cancellation notices, and medical records if needed.
Step 5: Submit the claim. Send the forms and proof the insurer asks for. Keep copies of all files and messages.
Step 6: Check the result. If the insurer denies your claim, ask for the reason in writing. Read the policy terms it used to make that decision. You can also ask your state insurance department about your options.
What Are the Disadvantages of Travel Insurance?
Travel insurance has limits that can affect your claim.
- Exclusions apply: A reason you feel is fair may not count as a covered event.
- Some costs remain unpaid: Policy limits and claim rules can reduce your payout.
- Pre-existing conditions may be excluded: Some plans offer a waiver if you meet set rules.
- Cancel for Any Reason costs more: This add-on often raises the price and pays only part of your trip cost.
- Claims need proof: Missing records can slow a claim or lead to a denial.
- Credits may affect payment: Refunds from airlines or hotels can reduce the amount you can claim.
Check your credit card benefits too. Your card may already cover some trip costs.
Is Trip Cancellation Insurance Worth Buying?
The value depends on how much money you could lose.
If you book a costly cruise, a long family holiday, or a trip with strict refund rules, cover may be useful. It can also help when a sudden illness could force you to cancel.
For a low-cost trip with free cancellation, a policy may add little value. First, check the refund rules for each booking. Then compare the cost of insurance with the money you could lose.
How Much Does Trip Cancellation Insurance Cost?
Many travel insurance plans cost about 5% to 10% of the total trip price. The final rate depends on your age, trip cost, travel dates, and chosen cover.
For example, a $3,000 trip may cost around $150 to $300 to insure. This is only a guide. Your actual quote may differ.
Compare the benefit limits, exclusions, and claim rules before choosing a plan. A low price alone does not show how well a policy fits your needs.
Frequently Asked Questions | Trip Cancellation Insurance
1. Can I get a 100% refund on a canceled flight?
Yes, in some cases. Your airline may offer a full refund under its fare rules or when refund laws apply. Travel insurance may also repay eligible non-refundable costs for a covered reason. Neither option guarantees a full refund in every case.
2. Which travel insurance is best for canceling for any reason?
Look for a Cancel for Any Reason (CFAR) add-on. It gives you more freedom to cancel for reasons outside standard cover. It often pays 50% to 75% of eligible trip costs. You must meet the plan’s purchase deadline and other rules.
3. What is not covered by trip cancellation insurance?
Common exclusions include a change of mind, known events, some pre-existing conditions, and reasons not listed in the policy. Work duties may also fall outside cover. Always read the full list of exclusions.
4. How much does trip cancellation insurance usually cost?
Many plans cost 5% to 10% of the insured trip price. The price changes with your age, trip cost, and level of cover. CFAR cover usually costs more.
5. What is a good medical reason to cancel a flight?
A serious illness or injury that makes you unfit to travel may qualify. The policy may require a doctor’s advice or medical proof. A mild illness does not guarantee a claim.
6. Which travel insurance should I avoid?
Be careful with plans that have unclear exclusions, low limits, strict claim rules, or weak support. Check the insurer’s license, read the policy, and confirm who handles claims. Ask your state insurance department if you have doubts.
Before you buy: Read the policy, check the cancellation rules, and save your booking records. These steps can help you make a clear choice and know what to do if your plans change.